
Family decisions have a habit of becoming financial decisions. A house move affects the mortgage and commuting costs. A different car changes insurance, fuel and monthly repayments. Even a phone contract can matter when several people in the household need one at the same time.
Before comparing deals, take an evening to reset the family finances. Pull together the household budget, upcoming costs and credit information. The exercise is less exciting than viewing houses or choosing a car, but it can prevent a mistake from surfacing after an application has already been made.
Begin with the decision and work backwards
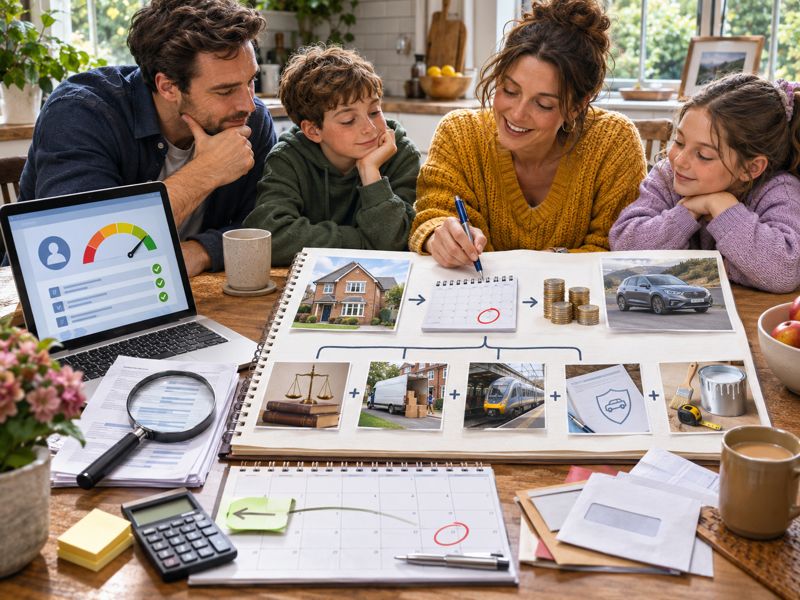
Write down what the family is considering, the likely date and the full cost. Include the expenses around the decision, not only the obvious price. Moving can bring legal fees, removals and higher travel costs. A car may need a deposit, insurance and repairs. A new monthly contract adds another fixed commitment to the household budget.
Next, decide when an application might be required. Credit-file problems can take time to investigate, so a check made the night before a mortgage appointment is little help. Allow several weeks where possible, particularly if you have moved recently, changed names or closed joint accounts.
Before comparing mortgages, finance agreements or new monthly contracts, give yourself time to find mistakes and query them. That starts with the simple job of checking and correcting your credit file, so lenders see accurate addresses, account histories, payment records and financial associations rather than an avoidable error that follows your family into the application process.
Read the report rather than chasing the score
A credit report records information such as names and addresses, electoral roll details, credit accounts, payment history, balances, defaults, court judgments, searches and financial associations. It does not normally show salary or ordinary day-to-day purchases.
The score displayed by an agency can be a useful warning light, but it is not a universal pass mark. Credit reference agencies use different scales, and lenders apply their own criteria. A high score does not guarantee acceptance; a low one does not explain which part of the application needs attention.
Read each account entry instead. Check whether the lender name is familiar, the address is correct, the balance looks plausible and payments have been recorded accurately. Look for duplicate accounts, settled debts still shown as open and searches you do not recognise. If anything suggests identity fraud, contact the relevant organisation promptly rather than waiting for a planned application. For large purchases such as buying a car ensure you choose a broker or lender who initially carry out a soft search, car finance can leave repeated searches on your credit file, more on car finance here.
Check more than one agency
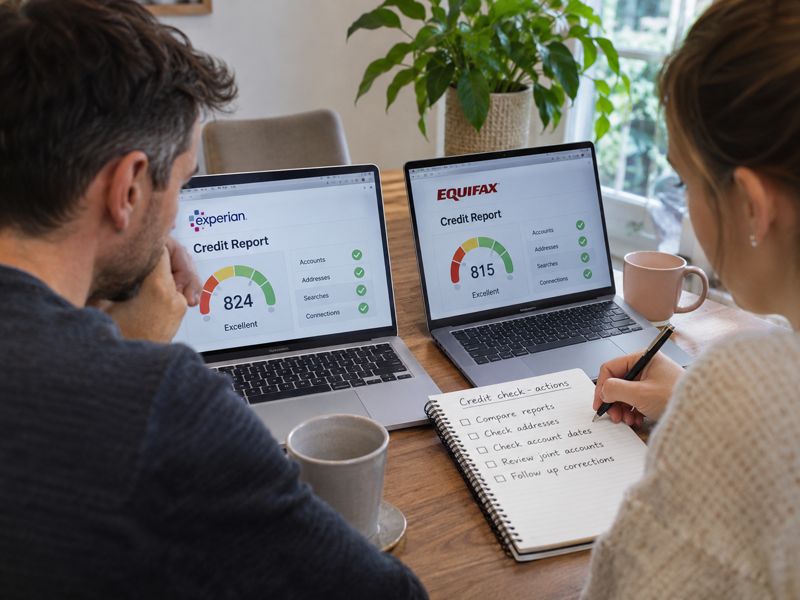
Banks, councils, utility companies and other organisations do not all send data to every credit reference agency. One report may therefore contain an account or correction that another does not. UK consumers can obtain statutory credit reports without paying, so there is no need to start a subscription simply to inspect the underlying data.
Checking your own report is a soft search and does not create the same application footprint as applying for credit. It is sensible to review reports from the agencies holding your information, especially before a mortgage, tenancy, car-finance agreement or another important commitment.
Keep a simple list of anything that needs action. One partner can gather reports while the other checks addresses, dates and joint accounts, but each adult should access their own information securely. Credit reports are personal records, even when the household makes decisions together.
Sort out old financial links
A joint mortgage, loan or bank account can create a financial association between two people. That connection may remain relevant to lenders while the joint financial product exists. Simply living with someone, marrying them or sharing an address does not by itself create the same link.
Check that current associations are expected. If a joint account with a former partner has been closed and there are no remaining shared financial commitments, ask the credit reference agencies about a notice of disassociation. Do not request one while a genuine joint account or debt is still active.
This is also a good moment to review how the household manages shared bills. Agree which account pays each commitment, how much each person contributes and who checks that the money has arrived before direct debits leave. A correct credit file will not protect either person from a missed payment caused by confusion at home.
Challenge mistakes with evidence
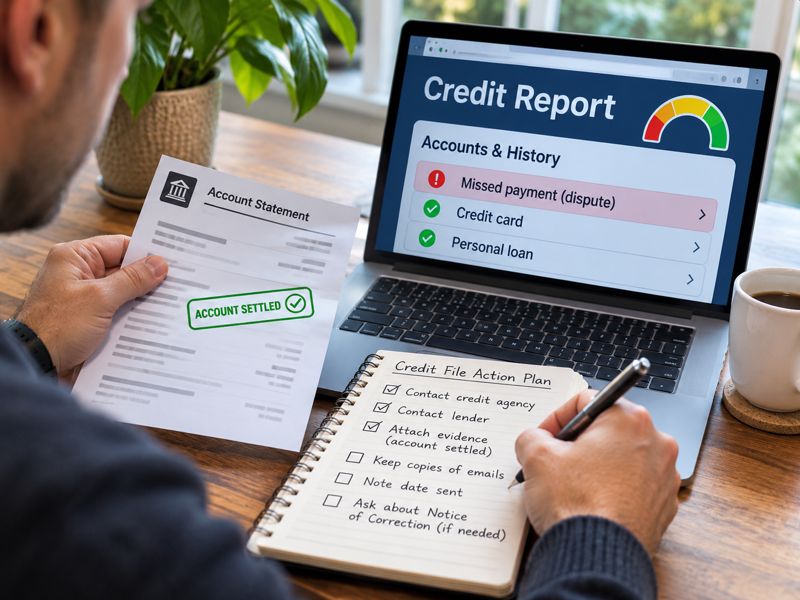
If an entry is wrong, contact the credit reference agency and the organisation that supplied the information. State exactly what is inaccurate and what the correct position should be. Attach only the evidence needed, such as a statement showing that an account was settled or proof of the correct address.
Keep copies of messages and note when they were sent. If the issue cannot be resolved immediately, ask whether a Notice of Correction is appropriate. This can add a short explanation to the file, although the better outcome is for inaccurate information to be investigated and amended.
Avoid companies promising to erase accurate missed payments or produce an instant credit transformation for a fee. Accurate negative information cannot simply be wished away. Time, consistent payments and lower borrowing can help, but there is no legitimate shortcut that guarantees approval.
Pause new applications while you prepare
An eligibility checker may use a soft search to estimate the chance of acceptance. A full application usually creates a hard search that other lenders can see. Several applications close together can make a difficult situation worse, so read the wording before entering details and do not apply merely to test the market.
Use the waiting period to steady the household budget. Bring overdue accounts up to date where affordable, avoid using more of a credit limit simply to improve appearances elsewhere, and keep money aside for the costs surrounding the family decision. Never miss an essential bill to make a deposit look larger.
Finish with an affordability check
Once the reports are accurate, return to the family budget. Test the proposed repayment alongside housing, food, childcare, energy, transport, existing debts and irregular costs. Use a demanding month rather than the cheapest month of the year.
Then talk through what would happen if income fell, childcare changed or the car needed work. A lender’s approval answers the lender’s question about risk and affordability under its process. It does not replace the family’s judgement about how much breathing room feels safe.
A family finance reset will not make every decision easy. It does make the next conversation more useful. You will know what the household can afford, what the credit reports actually say and which problems need fixing before an application turns them into an unwelcome surprise.