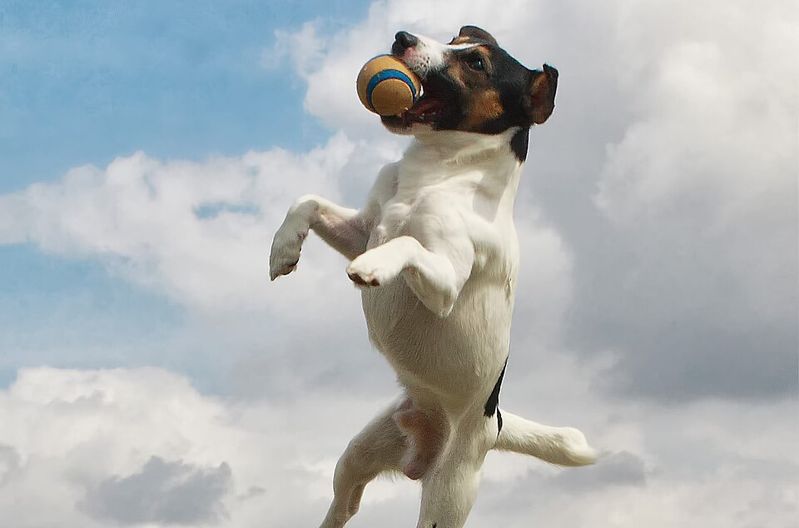
If you live with a Jack Russell, you already know that quiet moments are hard to come by. They are whirlwinds of energy. They believe that no garden fence is unscalable, no ball should go un-chased, and no rustle in the bushes can pass without a thorough inspection. While their spunky nature is a big reason we love them, owning one brings a fast reality check around healthcare and vet bills.
When looking into dog insurance, standard check-ups and routine vaccines are usually top of mind. The real test of a policy comes during an unexpected emergency or when managing a condition over a dog’s lifetime.
Understanding Breed Health Risks
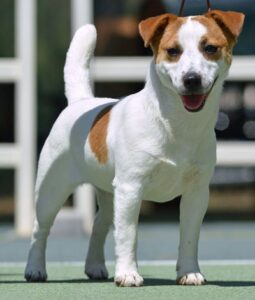

Jack Russells are active dogs, but they face a few known genetic health risks. Primary lens luxation and luxating patella show up regularly in breed health reports, and these two issues play out differently:
- Primary Lens Luxation: This occurs when the lens of the eye shifts out of place. It can turn into a clinical emergency within 24 hours as pressure builds inside the eye. An emergency out-of-hours assessment and hospital stay can cost between £1,000 and £2,500 depending on location and severity, even before specialized surgery.
- Luxating Patella: This happens when the kneecap slips out of its groove. A slipping knee often starts gradually. You might notice a small skip, hop, or limp in your dog’s gait that comes and goes for months before a vet makes an official diagnosis.
These conditions need different financial planning. An eye emergency requires money on hand right away, while a knee issue requires steady, long-term cover.
Medical History and Timing
Early clinical signs play a major role in how future claims are handled. Because a knee problem develops gradually, the very first note a vet writes in the medical record matters.
Most insurers enforce a 14-day initial waiting period for illnesses. A subtle skip in your dog’s step before cover starts or during those first two weeks gets classed as a pre-existing condition, meaning future claims for that knee will likely be turned down.
Even with policies that skip an upfront health declaration, the insurer reviews full medical records during your first claim. Sorting out cover early before symptoms end up in a vet record saves a lot of hassle down the line.
Managing Annual Limits and Excesses

When comparing insurance options, pay close attention to how fee limits and excesses work together:
- Shared Annual Headroom: A lifetime policy gives you an annual limit that resets every year when you renew. All eligible claims in a single year come out of that one allowance. A £2,000 eye emergency in spring leaves you with less available cover for knee management later that same year.
- Fixed Excesses Per Condition: While your annual limit is shared, your excess usually stays separate. Many policies charge a fixed excess per condition per policy year. Treating an eye emergency and a knee condition in the same 12-month period means paying two separate excesses.
Comparing how providers handle continuous care and annual limits is an important step when shopping around. Looking through options from pet insurance providers like Waggel helps ensure you pick a lifetime plan that resets every year, so a sudden emergency will not wipe out your safety net for ongoing treatment.
Peace of Mind for the Long Run
Nobody buys insurance hoping to use every penny of their policy. Having good cover simply means that when an unexpected bill lands, you can focus on getting your dog the right care without stressing over your bank balance.